You find out after it's already happened.
A month-end report is a photograph; the business is a film. By the time the ledger shows a miss, the intervention window has closed.
Credit Risk Orchestration · Nairobi
A read-only intelligence layer that shows you a business heading into trouble weeks before your own reporting does — early enough to restructure instead of write off. It sits on top of the core system you already run. No replacement, no downtime, and every credit decision stays with your committee.
Observed across deployments and pilots. Direction, not guarantees.
Banks, microfinance banks, SACCOs and digital lenders.
See distress earlier, restructure instead of writing off, and recover more of what you have already lent.
ExploreDFIs, impact lenders and programme managers.
Enforce mandates at origination, monitor downstream portfolios, and evidence where capital landed.
ExploreIf you insure, buy debt, or make introductions — we also work with insurers, distressed debt buyers and referral partners.
Start here
Send us a CSV export of your loan ledger — 24 months if you have it. We run it through UNBRDN and show you what our screen would have flagged, and when, against what actually happened. No integration, no IT involvement, no commitment. If it tells you nothing you didn't already know, that's a useful answer too.
Not through negligence. Through timing. Every part of a conventional credit process reports on the past, and the past is the one thing the person accountable for the loan portfolio cannot change.
A month-end report is a photograph; the business is a film. By the time the ledger shows a miss, the intervention window has closed.
Similar files, different officers, different outcomes. Portfolio risk you can't predict because the decisions weren't consistent.
When an auditor asks how a loan was approved, “the officer used judgement” is an increasingly difficult answer.
By the time the recovery team mobilises, the borrower is in crisis and most of the recoverable value has gone.
It is not a moral failure by lenders. It is an information failure, and that is solvable.
What UNBRDN does
UNBRDN reads from the systems you already run. All credit approvals remain with your own committee.
Recover more of what you have already lent.
Continuous monitoring of every account against your own policy thresholds, a structured turnaround path instead of a write-off, and a collections command centre for the accounts that do go bad. Promises kept, right-party contact and unworked case queues, tracked per collector.
Price the borrower on real cash flow, not a snapshot.
Upload an applicant book and every borrower is scored against your own debt service ratio threshold, your mandate and your risk limits. Bank and mobile-money statements read, normalised and turned into a decision-grade view.
Turn documents into a defensible credit view in minutes.
Borrower-level analysis producing an end-to-end financial profile, and standalone statement analysis focused on inflows, outflows and cash-flow signal.
Behind these three sit origination, mandates, market discovery, sustainable finance, transfer pricing and a debt marketplace. Ask and we will show you.
That third step is the point. A borrower you restructured who then repaid is someone you have seen under pressure — on any sensible measure a better risk than a stranger with a clean application.
A marketplace layer for portfolios that need to change hands is in development.
Most lenders never close this loop. The cured borrower is the best-qualified lead you already own.
Access
UNBRDN runs as a private, isolated workspace for each institution. Access is by invitation so your environment is provisioned and secured before anyone signs in.
Passkey authentication. No passwords, ever.
If you are a business carrying debt, run a free assessment yourself. Share a few details and get an analysis of your position and what to tackle first.
For commercial lenders
An account a week late is a timing problem. The same account at ninety days has already paid somebody else first, the goodwill is spent, and it is heading for classification, provision and security realisation. The money has not changed. The recoverability has.
For funds and development finance
Also serving
Distribution and risk data for embedded cover; the insurer remains risk carrier and product owner.
Propensity scoring so you know which accounts will pay before you bid.
Introduce a lender or fund and share in what your network unlocks.
Get in touchYour existing systems
UNBRDN intelligence layer
Outputs
Borrower data remains within the client-controlled deployment and approved data plane. VALR Extract and VALR Analyst can process documents locally, with external LLM egress disabled by default.
Reads bank and mobile-money statements. Resolves transaction direction against the running balance rather than inferring it from the description, because on a mobile-money statement the same paybill can be income for one borrower and an expense for another.
Reasons through the credit decision and produces a defensible, reviewable output.
We built two proprietary models — one that reads bank and mobile-money statements, one that reasons through the credit decision. Both are designed to run within the bank-controlled environment, so borrower data does not have to be sent to third-party LLMs to get a decision. In our own benchmarking they approach the quality of leading frontier models at a materially lower cost per decision.
Benchmark figures are from internal testing and describe direction, not a guaranteed result in any given deployment.
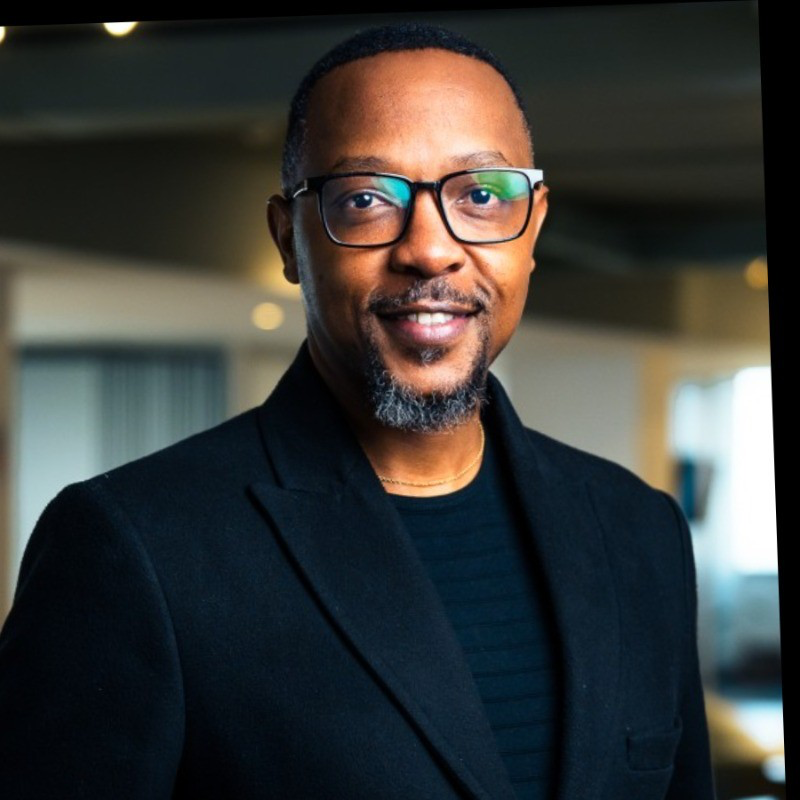
Founder & CEO
Two decades in credit recovery and SME lending.
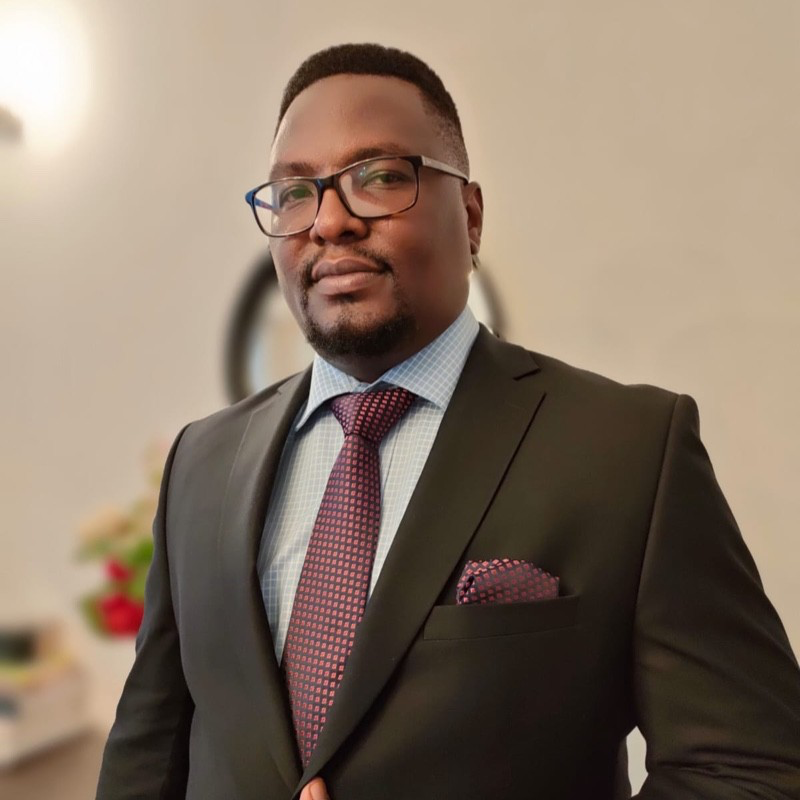
Co-Founder & CFO
20+ years in institutional credit risk. Founder Chairman, Association of Debt Recovery Agents Kenya.
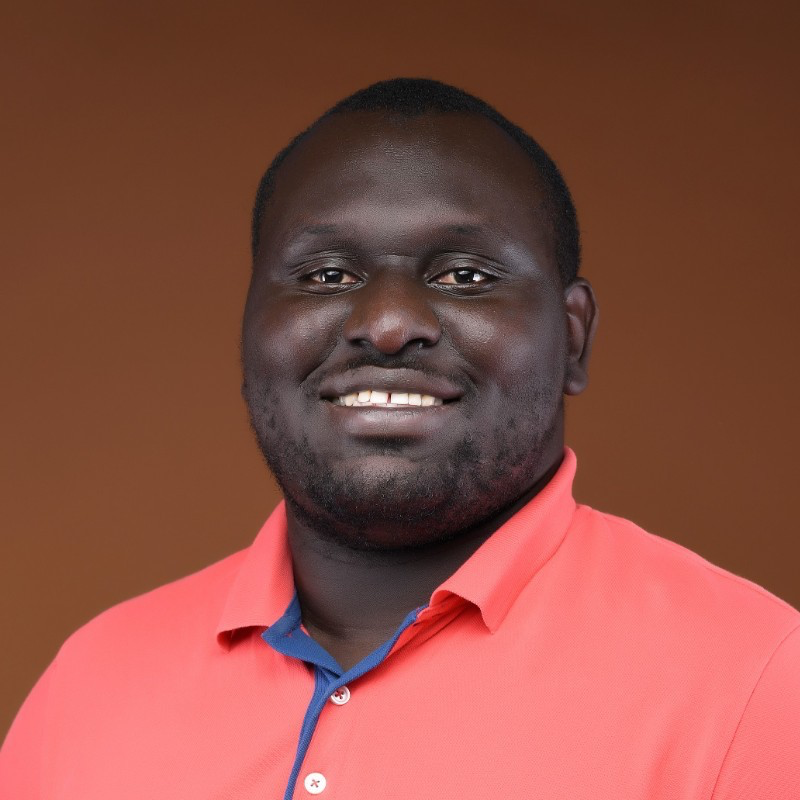
Co-Founder & CTO
Architect of the UNBRDN platform. Senior Software Engineering Manager at Microsoft.
We came at this from the recovery end. Twenty years on the wrong side of these decisions shows up in what we chose to build.
Observed across deployments and pilots — direction, not a guarantee.
Amber flags fire against your own thresholds, typically weeks before the ledger misses a payment. We do not publish a fixed prediction window, because the right window is the one your own policy defines.

 Nairobi International Financial CentreCertified — July 2026 cohort
A CSV export, a backtest, and an honest read of what our screen would have flagged and when. No integration, no commitment.
See what your own book looks likeOr just talk to a founder — support@valrcapital.co
Somewhere in your pipeline right now, a bankable borrower is being declined and a bad one approved because your system read one line on a statement backwards. It doesn't throw an error. It just quietly costs you. Here's the unglamorous problem at the front of every loan, and why the lenders who get it wrong never find out.
ReadThe World Bank’s fiscal warning highlights a major blind spot for regional leaders. Discover how non-invasive data infrastructure protects state funds and corporate portfolios from unseen shocks.
ReadDiscover how smart commercial lenders bypass multi-year IT integration delays to deploy instant portfolio risk surveillance layers.
Read